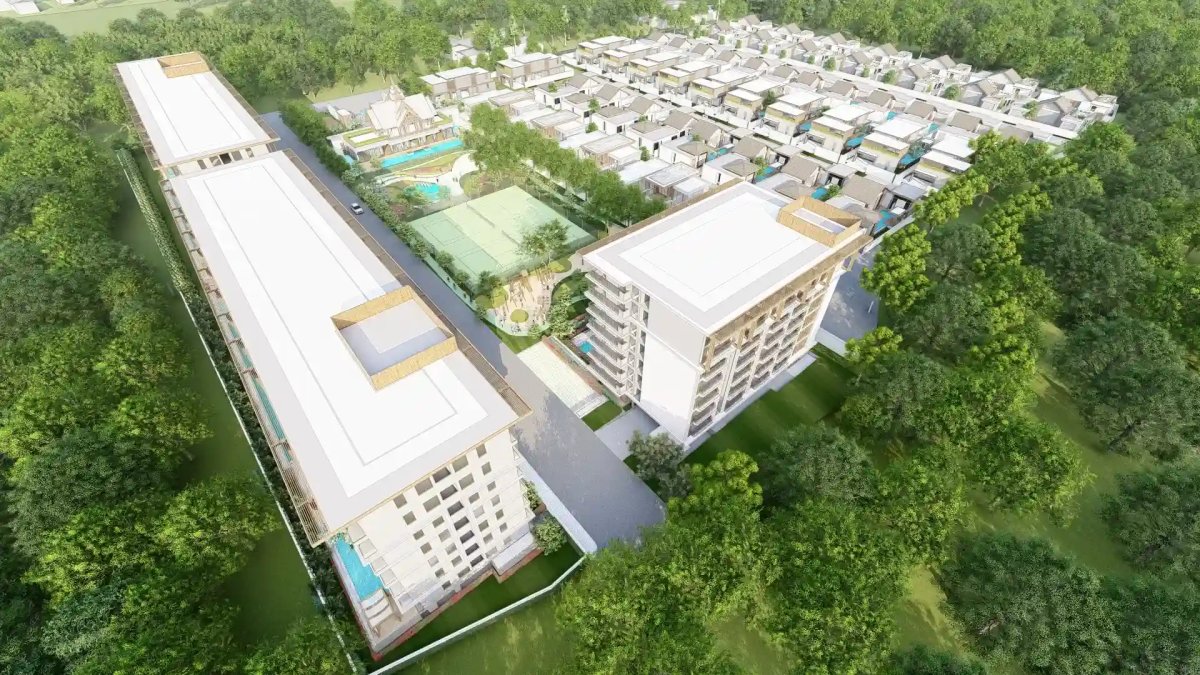
Best Banyan Group Projects in Phuket 2026: Ranked for Investors
Banyan Group offers five active or recently completed residential products in Phuket, spanning $160K (Cassia secondary) to $6.5M (Banyan Tree Oceanus). The right choice depends entirely on your budget, investment goal, risk tolerance, and timeline. This ranking breaks down each project by investor profile, with real numbers for yield, price per sqm, and delivery timeline.

Rank 1 (Entry Investor): Cassia Phuket: Best for Yield Percentage at Low Capital
For investors seeking the highest yield percentage on the lowest capital commitment within the Banyan Group / Laguna ecosystem, Cassia Phuket is the answer. Completed in 2019, generating income now, available from $160K on the secondary market, nothing else in Laguna Phuket matches Cassia’s accessibility.
Why it ranks first for entry investors:
- Completed and income-generating from day one of purchase
- Hotel-managed rental pool removes operational burden
- Income begins at purchase rather than at handover, and on a completed building an owner’s statement exists to be read before you commit, which no yield estimate can substitute for
- Full Laguna estate access: golf, spa, Boat Avenue, Bang Tao Beach
- Foreign freehold title available (subject to quota)
Best for: Investors with $150K-$375K seeking maximum yield percentage on minimum capital, or buyers who want passive income without construction wait.
Key limitation: Older building (2019), no sea view, smaller units (40-75 sqm), and competitive pressure from newer Lakelands projects ahead.
Rank 2 (Near-Term Appreciation): Skypark Elara Lakelands: Best Off-Plan
Skypark Elara is the most accessible off-plan Banyan Group project in Phuket in 2026, delivering October 2026, the shortest wait of any active off-plan project. With 220 units across three 7-floor buildings in Cherng Talay, it is part of the $2 billion Laguna Lakelands masterplan.
Why it ranks second:
- October 2026 delivery, income starts within months
- Part of the $2B Lakelands masterplan: infrastructure development benefits value long-term
- $6,100/sqm is reasonable for Laguna Phuket positioning
- 0% interest payment plan (20% across 5 stages)
- Lake views with Laguna Golf and Boat Avenue proximity
Unit breakdown:
| Type | Size | Price Range |
|---|---|---|
| 1BR | 57 sqm | THB 8.29M-~12M ($265K-$380K) |
| 2BR | 85 sqm | THB 15M-25M (~$470K-$790K) |
| 3BR | 141 sqm | THB 30M-47.45M (~$950K-$1.52M) |
Best for: Investors who want off-plan appreciation potential (construction to completion) with a delivery date close enough to limit carrying cost drag. Also suits mid-HNW buyers wanting Laguna access at below-Garrya pricing.
Key limitation: Lake view rather than sea view or beachfront; no direct beach proximity (shuttle/walk required).
Rank 3 (Wellness Premium): Residences at Garrya: Best for Wellness Brand
Garrya is Banyan Group’s most compelling mid-market product, 38 units, 200m from Bang Tao Beach, wellness brand with genuine ADR premium potential, and Q2 2027 delivery. The $8,300/sqm pricing is the premium you pay for the Garrya wellness concept and beachfront proximity.
Why it ranks third:
- 200m from Bang Tao Beach, closest to beachfront among all mid-market Laguna options
- Garrya wellness brand commands higher ADR than standard Laguna condos
- 38 units = scarcity relative to 220-unit Skypark Elara
- Interest-free payment plan (20% x 5 stages, THB 100K reservation)
- Q2 2027 delivery, 15-18 months to income generation
Unit breakdown:
| Type | Size | Price Range |
|---|---|---|
| 1BR | 57-58 sqm | From THB 15.4M (~$430K) |
| 2BR | 113-115 sqm | THB 28M-45M (~$780K-$1.26M) |
| 2BR Penthouse | 215-220 sqm | THB 50M-60M (~$1.4M-$1.68M) |
| 3BR Penthouse (rooftop pool) | Larger | Up to THB 67.7M (~$1.9M) |
Best for: Mid-HNW buyers ($430K-$1.9M budget) who want the beachfront lifestyle premium, wellness brand rental advantage, and a defined delivery timeline.
Key limitation: Highest price per sqm of all off-plan Banyan Group products ($8,300/sqm). For buyers prioritising value per sqm, Skypark Elara or Laguna Aster offer more space per dollar.
Rank 4 (Ready Luxury): Angsana Oceanview: Best Ready Branded Luxury at $
For buyers who cannot tolerate construction risk and want a completed, sea-view branded property in Laguna Phuket, Angsana Oceanview is the most accessible option. Completed 2021, 149 units, sea views, Angsana brand, available now with verifiable rental history.
Why it ranks fourth:
- Completed and generating verified rental income, no construction risk
- Sea views from Laguna Phuket position
- Angsana brand drives rental rates above non-branded alternatives
- 149 units means reasonable secondary market liquidity
- Historically appreciated 5-6%/year consistent with Laguna area
Best for: Buyers with $1.2M-$2.5M who want brand-backed, sea-view property in Laguna generating income from day one of purchase. Suitable for lifestyle buyers who plan personal use alongside rental.
Key limitation: a secondary-market premium, and whatever appreciation happened during construction has happened to somebody else. The net yield band this line used to give is withdrawn, Thailand keeps no letting register, so no Laguna net yield has been measured. What is quotable is the hotel programme’s share of gross, customarily 35 to 45% in a Laguna-managed pool, which is a large deduction on any revenue figure you eventually establish.
Rank 5 (Trophy Asset): Banyan Tree Oceanus: Best for UHNWI Capital Prese
Banyan Tree Beach Residences Oceanus is the most exclusive residential product in Phuket, 16 units, direct Bang Tao beachfront, delivering December 2028. For UHNWI buyers, this is a trophy asset with genuine capital preservation characteristics: brand equity, absolute scarcity, and beachfront irreplaceability.
Why it ranks fifth (not first, for most investors it is not accessible):
- Only 16 units, rarest Banyan Group product in Phuket
- Direct Bang Tao Beach position, cannot be replicated
- Banyan Tree brand drives highest ADR in managed rental
- 5-year payment plan with 3-7% financing
- Developer forecast yield ~5% annually
Best for: UHNWI buyers ($5M+ liquid) seeking capital preservation in a globally recognised luxury brand asset, with income yield. Not suitable for investors prioritising yield percentage or construction-era appreciation.
Key limitation: a $4.7M entry, a December 2028 delivery, so roughly three years before the building can let a single night, and a narrow resale market. The yield floor this line used to quote is withdrawn; there is no measured yield for it to be a floor of.
The Laguna estate book, in full
Rankings read better against the whole shelf. Our price list carries 15 Laguna and Banyan Group schemes with 430 priced units between them, and the spread inside that single estate is wider than the spread between most Phuket districts:
| Scheme | Priced units | Range (THB) | THB per sqm | Delivery |
|---|---|---|---|---|
| Laguna Golf Residences Hibiscus | 97 | 12,880,000 - 54,990,000 | 223,333 | Q4 2029 |
| Laguna Lakelands Waterside | 69 | 8,000,000 - 37,910,000 | 171,714 | Q3 2027 |
| Skypark Elara Lakelands | 62 | 8,290,000 - 47,450,000 | 187,222 | Q3 2028 |
| Laguna Beach Residences Bayside | 52 | 27,700,000 - 102,300,000 | 272,842 | Q1 2029 |
| Laguna Aster (Lakeside 2) | 49 | 10,500,000 - 24,170,000 | 214,286 | Q2 2028 |
| Garrya Residences | 35 | 16,360,000 - 120,220,000 | 312,259 | Q2 2029 |
| Bellaguna Lotus | 16 | 19,550,000 - 112,410,000 | 299,508 | Q4 2029 |
| Laguna Beach Residences Seashore | 12 | 22,700,000 - 34,300,000 | 238,168 | Q4 2026 |
| Tri Vananda | 9 | 54,383,017 - 147,868,875 | 203,657 | Q2 2027 |
| Banyan Tree Beach Residences Oceanus | 7 | 160,000,000 - 391,000,000 | 452,479 | Q4 2028 |
| Laguna Lakelands Waterfront Villas | 7 | 54,800,000 - 84,000,000 | 126,619 | Q3 2027 |
| Banyan Tree Residences Beach Villas | 6 | 106,900,000 - 245,000,000 | 376,370 | Q2 2028 |
| Banyan Tree Beach Residences Nammu | 5 | 110,000,000 - 116,000,000 | 247,863 | Q2 2026 |
| Angsana Oceanview Residences | 3 | 45,820,000 - 84,940,000 | 219,234 | Q1 2026 |
| Laguna Reef (Beachside) | 1 | 27,000,000 - 27,000,000 | 206,107 | Finished |
Three things that ranking cannot show you but this table can.
The metre ranges from 126,619 to 452,479 THB inside one estate, a factor of 3.6. Buying “in Laguna” says almost nothing about what you are paying per square metre; the scheme decides that, and the villas at Lakelands Waterfront are the cheapest metre on the whole shelf while the Oceanus beach residences are the dearest on the island.
Almost nothing is finished. Of the 430 priced units, exactly one sits in a completed building, a single unit at Laguna Reef. Everything else delivers between Q1 2026 and Q4 2029, so for practically every scheme on this page the juristic person’s accounts, the sinking fund history and an owner’s statement do not yet exist. That is the honest constraint on any Laguna purchase today, and no brand strength alters it.
The delivery dates run four years out. Three schemes hand over in 2026, three in 2027, four in 2028 and four in 2029. A buyer choosing on income timing rather than on brand should read the right-hand column first.
What All Banyan Group Projects Share
- Location in Laguna Phuket: the appreciation rate and gross yield band this line used to give are withdrawn, no transaction index and no letting register exist in Thailand, so neither has been measured. What the price list does show is that the Bang Tao corridor holds 4,589 priced apartments and 446 of the island’s 871 finished ones, which is the deepest market on Phuket by a wide margin and the substantive reason to buy in it
- Brand-managed rental: All projects offer or are eligible for Banyan Group managed rental programmes
- Laguna estate benefits: Golf, spa, Boat Avenue, Bang Tao Beach
- Foreign freehold availability: Condominium units eligible for foreign ownership under Thai law
- International buyer recognition: Brand equity reduces resale friction globally
Pros and Cons (Overall Banyan Group Portfolio)
What the brand premium buys:
- A managed rental programme with distribution and standards already in place, rather than an operator you have to find and vet yourself
- Access to the Laguna estate: golf, spa, Boat Avenue and Bang Tao Beach, infrastructure no standalone building can reproduce
- A quality signal at resale that shortens the next buyer’s research and widens the international audience
- Supply constrained by the estate boundary rather than by a developer’s current pricing, which is the one protection that does not expire
- Freehold availability for foreign buyers within the building’s allowance, on units an international purchaser recognises
What to consider:
- Brand premiums mean higher price-per-sqm than non-branded Phuket alternatives
- Management fees of 30-40% of gross rental create gap between gross and net yield
- Off-plan projects (Garrya, Elara, Oceanus) require 1-3 years before income generation
- Garrya at $8,300/sqm is expensive by Phuket standards; only justified if wellness ADR premium is realised
Buyer scenarios
Scenario A: Yield-first investor with a defined capital limit ($160K-$430K)
Cassia on the secondary market is the entry point, and the argument is straightforward: income from the first month, a letting record you can verify rather than project, and no construction risk. Ask for twelve months of actual distributions on comparable units rather than an annual average, and apply the full deduction stack before comparing the percentage with anything. The trade you are accepting is that the appreciation inside the estate has already happened on this stock; you are buying the income, not the uplift.
Scenario B: Mid-HNW wellness and beach proximity ($430K-$900K)
Reserve Garrya 1-2BR for 200m beach proximity and wellness ADR premium from Q2 2027. Accept higher price per sqm ($8,300) for scarcity (38 units) and beach walkability. Model personal use of 4-6 peak weeks, blocking those weeks drops net yield 1-2 points. Cross-read Phuket rental yield guide for net benchmarks.
Scenario C: Long-horizon buyer treating the estate as the asset ($900K+)
At the trophy end, the unit matters less than the position and the brand agreements behind it. Everything that makes a branded residence worth its premium, the management standard, the servicing, the resale recognition, the access to hotel facilities, is delivered through contracts rather than through the name on the building. Read those agreements before the price is negotiated, establish who is bound and what happens if the brand relationship changes, and set the holding period honestly: if the capital may be needed inside five years, this is the wrong asset however good the residence.
Risks and what to check before reserving
Four things decide whether the branded premium is recovered, and each is a document rather than an impression.
The first is the fee stack. Management on branded programmes commonly runs 30-40% of gross revenue, which is a real service and a large deduction. Get the full annual schedule in writing: the base management percentage, the common area maintenance rate per square metre, the sinking fund contribution, and any onboarding or exit fees. A yield quoted before those is a revenue figure, not a return.
The second is personal use, which is where owners are most often surprised. Participation agreements typically confine owner nights to pre-agreed windows outside peak demand, because those are exactly the weeks the programme needs to perform. Blocking four to six peak weeks moves net yield by one to two points. Read the personal use provisions in the participation agreement, which is a separate document from the SPA and is usually signed at or shortly after it.
The third is the foreign allowance. Ask the juristic person for a dated letter stating the remaining foreign freehold floor area against your specific unit; the 49% is measured against the building’s total floor area rather than its unit count, and it is consumed when buyers register rather than when they reserve.
The red flag to watch for is an appreciation figure quoted without the period and the sample behind it. Historical estate-wide appreciation describes the projects that completed and let well, not all of them, and a launch-to-handover gain is neither annualised nor realised until someone buys it from you. On off-plan stock, ask instead for the developer’s originally advertised handover dates against the actual ones, project by project.
What the Laguna estate actually adds
The premium over comparable non-branded Phuket stock is real, and it is worth being specific about what it pays for rather than accepting it as a brand tax.
The first component is infrastructure that already exists. Across roughly a thousand acres between the beach and the Cherng Talay lagoons, the estate gathers hotel brands, two eighteen-hole courses, Canal Village retail and a private beach club into a walkable resort ecosystem that nothing else on the island reproduces at that scale. A standalone building two streets away has access to none of it, and no developer can build it after the fact.
The second is the guest flow that comes with it. Owning inside the estate, or immediately beside it, means proximity to a captive audience generating well over a million guest nights a year, and that audience supports both nightly rates and occupancy floors in a way an isolated building cannot.
The third is a maintenance standard set by hotel operations rather than by a residential committee, which matters more over a decade than it does in year one. Buildings age at very different rates depending on who is responsible for them, and it shows in resale photographs long before it shows in a survey.
The fourth is supply constraint. Inside a defined estate boundary, comparatively little new stock can appear; in the wider corridor a great deal can and does. That is the one advantage that does not erode, and it is the strongest single argument for paying inside the boundary rather than beside it.
What the premium does not buy is exemption from the arithmetic. A branded unit at a 30-40% management fee has to earn more gross than a non-branded unit at 20-25% simply to match it on net, and whether it does is a question about the specific building rather than about the estate.
Compare a Banyan Group unit against the alternative on the same numbers
We model branded and non-branded stock side by side: full fee stack, personal use taken out, and the realistic exit.
Off-plan vs secondary: Banyan Group decision table
Frequently Asked Questions
None can be ranked, and the yield band this answer used to give for Cassia and Garrya is withdrawn: Thailand keeps no letting register, so no Banyan Group scheme has a measured yield. The distinction that does hold is timing and evidence. Cassia and Angsana Oceanview are completed, so income begins at transfer and an owner's statement can be requested; Garrya delivers Q2 2027 and Oceanus in 2028, so both are estimates about buildings that do not yet exist. Ask any operator for twelve months of statements from a comparable let unit, on the completed schemes that is a reasonable request, and on the off-plan ones it is impossible, which is itself the answer.
Skypark Elara Lakelands delivers in October 2026, the soonest of all active off-plan Banyan Group projects. Garrya follows in Q2 2027, Laguna Lake Residences Aster in December 2027, and Banyan Tree Oceanus and Varuna in 2028. Cassia and Angsana Oceanview are already completed.
At exactly $500K, you can access a 2BR Skypark Elara or a 1BR Garrya. Skypark Elara offers more space per dollar ($6,100/sqm vs $8,300/sqm) and earlier delivery (October 2026). Garrya offers beachfront proximity (200m from Bang Tao Beach) and wellness brand premium. If yield and space per dollar matter most: Elara. If beachfront lifestyle and brand premium matter most: Garrya.
It cannot be established from published data, and the two appreciation figures this answer used to give are withdrawn. The Land Department registers transfers but publishes no price series for Phuket by area, by scheme or by purchase type, so neither an annual Laguna rate nor a reservation-to-completion figure has been measured by anyone. Brand equity plausibly supports resale, and the corridor is genuinely the deepest market on the island, 4,589 priced apartments and 446 of the island's 871 finished ones, but depth of market is an argument about how easily you will find a buyer, not about the price you will get.
On timing and evidence rather than on returns. Off-plan (Garrya, Elara, Oceanus) means a lower entry price and one to three years before any income, with nothing to inspect but renders and a specification; the construction-era appreciation figure this answer used to attach to it is withdrawn, because no such series is published. Secondary market (Cassia, Angsana Oceanview) means income from transfer, a building you can walk, a juristic person whose accounts you can read, and any letting history existing as statements rather than as a projection. Budget, risk tolerance and income timeline are the decision drivers; a yield comparison is not available to be one.
Pricing, remaining allowance and handover dates across the Banyan Group pipeline move through the year, and the secondary market inside Laguna moves independently of the launches. We track both, and we will say when a secondary unit beats an off-plan one on the same budget.
Read Also:

Maksim Shchegolev
Founder, MORE Group
Founder of MORE Group. Four years in investment banking before moving to Phuket, where he has worked in the local property market since 2018. Oversees developer relationships and every engagement above $300K.
About MORE Group →Get a Focused Phuket Property Shortlist
Share budget, area and goal. We will reply with suitable live projects, not a generic catalogue.
