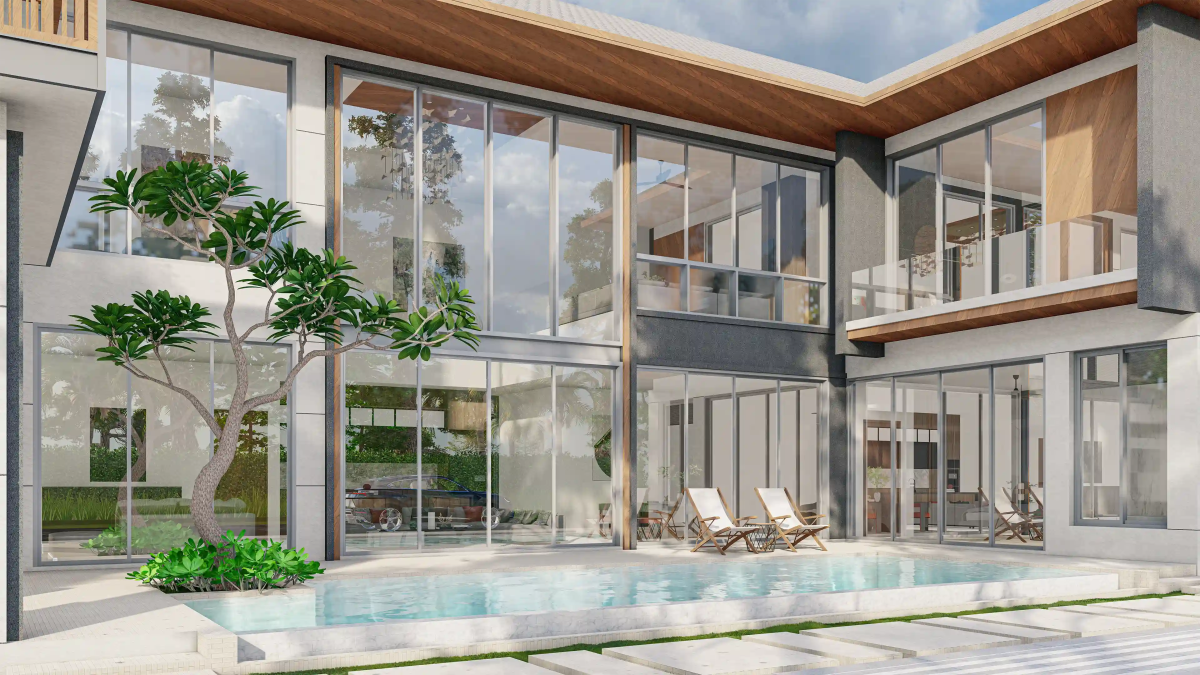
Quick answer: The best new projects in Phuket in 2026 range from 4.4M THB boutique condos at Kata Beach to 75M THB finished pool villas in Layan. The pipeline is the most varied in a decade, boutique developers, established Thai builders, and branded-residence operators are all active simultaneously. What separates the worthwhile launches from the noise is developer track record, location fundamentals, and honest yield assumptions. This guide covers the specific projects MORE Group is actively recommending to clients in mid-2026, with verdicts, price data, and what each project is genuinely best for.
Why 2026 is a genuine entry window (not a marketing tagline)
Several structural factors converge in 2026 to make this a real window rather than manufactured urgency:
| Factor | 2026 reality |
|---|---|
| Tourism | Airport at record capacity; rental ADR models now use 2024-25 actuals |
| Land costs | Bang Tao land up 40-50% since 2019; today’s launches price older land acquisitions |
| Developer competition | More quality builders active simultaneously than any prior cycle |
| Demand nationality mix | European, Russian, Chinese, and Middle Eastern pools all active |
| Near-completion options | Several 2023-24 launches now nearly delivered, residual risk is minimal |
| Airport expansion | Phase 2 expansion under planning; connectivity tailwind for northern Phuket |
Buyers who wait for “more clarity” typically pay completion premiums while bearing none of the construction discount. In 2026, the more relevant dilemma is choosing between a lower-priced 2028-delivery launch and a near-complete project that has already absorbed most of the risk.
How MORE Group selects projects to recommend?
1. Developer track record, Has the developer delivered a comparable project on time in Phuket? We check completed towers, not just renderings. First-delivery risk is real even for companies with national reputations in Bangkok.
2. Location fundamentals, Is there genuine tourist demand, infrastructure, and owner resale liquidity? A 20% launch discount is meaningless if the location can’t sustain occupancy.
3. Pricing integrity, Does launch pricing reflect comparable completed stock, or is it inflated against phantom “future values”? We model backward from rental comps and completed sales.
4. Yield mechanism, Is the rental program credible? We look for named management operators, sister-building track record, and net yield figures (not gross-with-guarantee marketing numbers).
5. Legal cleanliness, EIA approval, building permits, foreign quota confirmation in writing, and milestone-linked payment schedule, all non-negotiable.
Projects that clear all five are presented to clients. The ones on this page have cleared the bar.
Budget tier breakdown
Wekata 3 (Kata Beach, 4.4M THB) is fully furnished, boutique at 130 units, and delivers Q1 2027. The Kata location has over a decade of proven short-stay occupancy data. Fully furnished at entry price is unusual, most developers charge a separate furniture package of 300-800k THB on top of the base unit price.
Dominion Rawai (4.99M THB, 68 units) is near completion, which changes the risk profile entirely. Rather than waiting 24-36 months for delivery, buyers here are looking at a few remaining months of construction. South Phuket’s Rawai corridor has strong year-round rental demand and a residential community feel that retains long-stay tenants.
The Title Balcony sits at the absolute entry of the price range, around 3-4M THB for smaller units. The Title Group has a proven track record in Rawai and Kamala, and their managed rental program has documented occupancy data from prior completed buildings, this is the most important data point for yield-seeking buyers.
Mid-range tier: 7M-20M THB: Skypark Elara Lakelands
The 7-20M THB band is the most fragmented in 2026, many projects are competing for a buyer pool that wants Bang Tao access without the luxury villa price tag. Skypark Elara Lakelands, positioned in the Laguna corridor, targets this segment with premium mid-range product near the Laguna resort complex.
The Laguna area benefits from Banyan Tree, Anantara, and Cassia infrastructure, restaurants, golf, beach club, which supports both short-stay ADR and owner quality of life. See Laguna off-plan investment 2026 for the full corridor context.
Luxury tier: 20M THB and above: Mono Oxygen, Rainpalm, ISOLA
This segment behaves differently to the condo market. Buyers are typically buying partly for personal use, with yield as a secondary consideration. Scarcity is the dominant pricing factor, a 5-villa development cannot replicate itself, while a 300-unit condo can always launch a Phase 2.
Top pick: Best for immediate letting: Wekata 3
Wekata 3 sits in Kata Beach, one of the most consistently occupied tourist zones on Phuket’s west coast. Kata has a beach infrastructure, a range of restaurants and bars, and direct connectivity to Patong without the nightlife intensity, the profile attracts couples, families, and solo travellers across a long season.
Key data points for the yield thesis:
- Entry price: 4.4M THB fully furnished, comparable projects in the area without furnishing start at 5-6M THB when furniture package is added
- Unit mix, from the records rather than the brochure: of the 35 priced units, 21 are one-bedroom, 12 are two-bedroom and 2 are studios, so this is not the studio-led scheme this line used to describe, and the 64 sqm median puts most of it well above the size at which a twelve-month tenancy stays available
- Management: boutique on-site management expected, confirm operator name before reserving
- Delivery: Q1 2027, short construction window, milestone risk is relatively low
- Scale: 130 units in the scheme, of which 35 are priced on our list. Large enough to justify a professional management desk, small enough not to flood the local short-let market on its own, though what matters more is how much else completes in Kata at the same time, and the area holds 1,048 priced apartments with none finished
- Yield: not stateable. The “comparable Kata short-stay data” this line cited does not exist in published form, Thailand collects no occupancy or achieved rate for privately owned units, so both the gross estimate and the net derived from it are withdrawn. What is contractual is the fee: 30-40% of gross on a managed short-stay programme, which is the largest single deduction and the one to get in writing
- On the price list: 35 priced units from 4,400,000 THB, median 9,540,000, at 157,031 THB per square metre against a Kata area median of 152,000, so a small premium to its own corridor rather than a discount
For a first Phuket purchase with a yield priority, Wekata 3 is the most straightforward case in 2026. Fully furnished delivery at 4.4M THB means the total investment is predictable, no furniture package negotiation, no furnishing project managed from overseas.
Top pick: Best for lifestyle: ISOLA Phuket
ISOLA Phuket is already complete, the 12-villa development in Layan is delivered, and a handful of units remain available between 35M THB and 75M THB. This matters enormously: buyers see exactly what they are purchasing, visit the actual finished villa rather than a showroom, and can move into or begin renting immediately.
Layan is one of the quietest and most private areas of Phuket’s west coast, north of the Bang Tao beach clubs, with a lagoon, mature vegetation, and an established community of long-term residents and second-home owners. The beach is less than 10 minutes on foot from the ISOLA site.
What ISOLA delivers at the 35-75M THB tier:
- 12 villas only, the development will never expand; scarcity is permanent
- Finished construction, no delivery risk, no construction-site noise during visits
- Private pool per villa, tropical lifestyle standard at this price
- Layan location, quieter than central Bang Tao, stronger long-stay rental profile, preferred by European owner-user buyers
- Yield: not stateable, and both figures this line used to give are withdrawn. The structural point they were dressing is sound and does not need them: at a 35M-to-75M THB base, a rental programme has to generate several times the rent of an entry condo to reach the same percentage, and villa operating costs (pool, garden, staff, structure) are carried by the owner rather than shared through CAM
- On the price list: two priced villas remain, at 35,000,000 and 75,000,000 THB, at 125,000 THB per square metre on a 600 sqm median
For a lifestyle buyer who wants Phuket’s best address without construction uncertainty, ISOLA is the 2026 pick. The 35M THB entry is the lowest available for finished product of this quality in the Layan/Bang Tao premium corridor.
View full ISOLA Phuket details →
Top pick: Best for scarcity: Mono Oxygen Bang Tao Phase 2
Mono Oxygen Bang Tao Phase 2 is pricing at 23.95M THB for pool villas in Choeng Thale, the heart of the Bang Tao corridor. Phase 2 delivers Q2 2027 and has five units total, that is not a typo. When five villas sell out, this product ceases to exist.
Why scarcity matters for appreciation:
- Land in Choeng Thale is effectively exhausted for boutique villa development, new projects are either high-rise condos or priced at multiples of 23M THB because there is no land left for smaller developers to acquire affordably
- Five units absorb entirely from a small buyer pool, even one or two resale transactions in the first 3-5 years can establish a new pricing benchmark with no competitive supply to suppress it
- Bang Tao rental premium, short-stay ADR in Bang Tao runs 20-30% above Rawai on comparable unit types, supporting the higher entry price
The 23.95M THB price point reflects Bang Tao land cost reality, not developer greed. Whether comparable Botanica villas that delivered nearby in 2022-23 have resold at a premium is not something anyone can show (Thailand publishes no transaction register) and the claim this sentence used to make about them, and about the corridor historically outperforming the island on appreciation, is withdrawn. Buyers here are not running a yield calculation; they are buying scarcity, which is countable: five villas.
View full Mono Oxygen Phase 2 details →
Top pick: Best entry price and lowest total cost: Wekata 3
For a buyer whose primary concern is capital preservation and predictability of total spend, Wekata 3 is the clearest case in the 2026 pipeline, and the reason is what the entry price includes rather than what it is.
Fully furnished at 4.4M THB. Most developers price the unit and then sell a furniture package separately, commonly 300,000-800,000 THB on top. A furnished delivery removes that negotiation, removes the risk of specifying a fit-out from overseas, and makes the total figure the figure. For a first purchase managed remotely, that is worth more than a marginally lower headline price on an unfurnished unit.
A boutique count at 130 units. Large enough for a functioning juristic person and a real service charge base, small enough that your unit is not competing against two hundred identical listings every handover season.
A location with occupancy history rather than an occupancy projection. Kata has more than a decade of short-stay data behind it, across a long season and a tenant mix that is not dependent on one segment.
Q1 2027 delivery, which is a short off-plan window by the standards of the pipeline.
What you are not buying here is scarcity. This is standard product in a proven location, and it will have comparables at resale. That is precisely why it is the predictable choice: the price is discoverable in both directions, which cuts the upside and removes most of the guesswork.
Near-completion advantage: Dominion Rawai as the 2026 case study
Dominion Rawai (68 units, Rawai) is the clearest example. The project launched in 2023-24, sold well, and is now in the final stages of construction. Buyers entering today face:
- A residual price gap vs completed comparable stock, the off-plan discount hasn’t fully closed
- Minimal remaining construction risk, structural work is done, fit-out is progressing
- Delivery timeline of months, not years, buyers can start rental income in 2025-26 rather than 2027-28
- South Phuket Rawai fundamentals: a resident community, a lower metre than Bang Tao (145,000 THB/sqm against 161,000), and, because the scheme is near completion, an operator who can be asked for statements rather than projections
The argument against near-completion buying is the smaller headline discount. In early-stage off-plan, buyers sometimes see 20-25% below forecast completion value. Near-completion buyers might see 8-12% remaining gap. The counter-argument: an 8-12% discount with a 6-month wait is often better risk-adjusted than a 20% discount with a 30-month wait, especially for buyers who don’t want their capital sitting in construction-phase installments.
View full Dominion Rawai details →
Rainpalm Villas: modern tropical at Bang Tao/Surin scale
At 21 villas, Rainpalm has more scale than Mono Oxygen but less than a typical condo block. The size supports a credible management operation while maintaining boutique exclusivity. The 24.2M THB entry is accessible for buyers who want villa lifestyle without the 35M-75M THB ISOLA ticket.
Bang Tao/Surin context for villa buyers in 2026:
- Surin is often described as Phuket’s most liveable beach, quieter than Bang Tao central, within reach of the beach clubs, strong year-round residential feel
- Villa rental in this corridor targets high-spend European and Australian holidaymakers, supporting ADR above 15,000 THB/night on premium product
- Land for new villa development is increasingly scarce, as with Bang Tao; Rainpalm’s 21 units are among the last boutique villa sites in this immediate area
View full Rainpalm Villas details →
Looking for the right property in Phuket?
Our experts send a shortlist within 2 hours. 0% buyer commission.
2026 market context: which areas are rising, which are overbuilt
Bang Tao / Laguna corridor, supply-constrained
This is the highest-demand zone and also the most land-constrained. Developers who acquired land pre-2021 are launching at prices that reflect their lower cost basis; any developer acquiring land today faces 30-50M THB+ per rai for beachside plots, which pushes new project pricing above 8-10M THB for a 1BR unit. Buyers in 2026 still benefit from projects where land was acquired earlier, but that window closes as old parcels are developed.
Rawai / Kata / south Phuket, value, stable occupancy, growing
South Phuket remains the value corridor, and by less than this paragraph used to say: Rawai’s metre runs about 10% below Bang Tao’s on our list (145,000 THB/sqm against 161,000) not 30-40%. What the area has is a mature tourist infrastructure, a resident tenant base that does not track the high season, and a 46 sqm one-bedroom median that keeps a twelve-month tenancy available; that produces a different profile (steadier, less exposed to the calendar) rather than a measured return, since none is published.
Patong / Karon fringe, avoid for investment, consider for personal use
Patong has significant condo oversupply relative to quality tourist demand. Yield guarantees in this area frequently mask management programs that struggle to achieve brochure occupancy rates. We do not recommend new investment projects in central Patong for buyers prioritising returns. For buyers who want to be near Patong’s nightlife and entertainment for personal use, the picture is different.
Phang Nga / north of airport, speculative, infrastructure-dependent
Some developers are promoting projects north of the airport on the basis of “future” infrastructure. We treat these as speculative until concrete government spending is confirmed and measurable. For first purchases, stick to established demand corridors.
Off-plan vs ready-to-buy: the 2026 perspective
The case for off-plan 2028-29 delivery:
- 15-25% discount vs forecast completion value on strong launches
- Staged payments spread capital over 24-36 months
- Best unit selection while quota is open
- Phuket’s track record of near-zero developer defaults on major launches
The case for near-completion or finished projects:
- Delivery in months, not years, rental income starts sooner
- Residual discount is smaller (8-15%) but risk is minimal
- You can inspect the actual finished unit
- No construction noise or site inconvenience during owner visits
- Management desk already operational in many cases
MORE Group’s 2026 recommendation: For buyers who need rental income within 18 months, prioritise near-completion (Dominion Rawai) or finished (ISOLA). For buyers who can tolerate a 24-36 month wait and want maximum capital efficiency, early-stage launches (Wekata 3, Mono Oxygen Phase 2) offer the better headline discount.
Payment plans: what developers are offering in 2026
| Pattern | Typical structure | Risk profile |
|---|---|---|
| Standard three-stage | 20-30% reservation/SPA + 20-30% construction milestones + 50% completion | Balanced, widely used |
| Milestone-linked | 20-30% SPA + 5-10% per major milestone (foundation, frame, fit-out, completion) | Best visibility, low concentration |
| Two-stage (aggressive) | 30% SPA + 70% completion | Higher completion concentration risk |
| Developer financing | 10-20% down, developer holds note | Read terms carefully, rates and penalties vary |
Red flag: Any developer requesting over 30% before ground is broken is outside normal practice for reputable Phuket developers. This is not a grey area, walk away.
FX note: USD and EUR buyers face THB movement during a 2-3 year build period. Historical THB/USD variance over 24-month windows has been modest (roughly 5-8%), but model a 5% adverse swing on final tranche to stress-test your budget.
Red flags for new projects in 2026
- No completed comparable project from the same developer
Every developer claims future delivery. The only meaningful evidence is a building they have already handed over, on time, at spec. If a developer’s pitch is “this is our first project,” price accordingly (significantly discounted for first-delivery risk) or wait until their first project delivers.
- Over 300 units in a single building
Large projects flood the local rental market at completion. Every unit competes with every other unit in the same building for the same guests on the same booking platforms. Boutique projects under 150 units maintain scarcity in the local rental supply.
- No named management company
“We will have professional management” at launch is meaningless. Demand the operator name, verify their track record at other Phuket buildings, and check their online reviews from existing owners. Anonymous management promises frequently become owner-managed buildings after handover.
- No escrow or milestone payment protection
The best-structured developers hold buyer payments in escrow or release them to construction only at verified milestones. If the developer cannot describe this structure, your money moves into their operating account from day one.
- Yield guarantees without a funding source
A guaranteed double-digit yield for five years sounds attractive, and the first thing to notice is that it cannot be a measurement: no Phuket yield is published, so nothing was measured for the guarantee to be set against. Ask who funds it, from what, and whether it is covered by rental income or subsidised out of the development margin. Guarantees funded from the sale price itself simply return your own money. After the guarantee period, you are left with a building that never built real rental occupancy.
- Reservation pressure without a lawyer review window
Any legitimate developer offers 14-30 days between reservation and SPA signing to allow independent legal review. If the sales team is creating “48-hour close-out” pressure, that urgency is a tactic, not scarcity.
How foreign buyers complete a purchase: the process
- Reservation agreement: typically 50,000-300,000 THB to hold a unit; often refundable within 7-14 days if you choose not to proceed
- Engage an independent Thai lawyer: this is not optional; your lawyer reviews the SPA, confirms EIA and permit status, and verifies foreign quota allocation
- Sign Sale and Purchase Agreement (SPA): legally binds both parties; your lawyer should have reviewed every clause before you sign
- Down payment: 20-30% of purchase price, typically within 30-60 days of SPA; must arrive as a Foreign Exchange Transaction (FET) wire in your name from abroad
- Construction milestone payments: each payment requires its own FET documentation; your lawyer builds a tranche matrix before the first wire so you are not creating FET gaps
- Completion and transfer: final 10-30% on delivery; title (Chanote or Nor Sor 3 Gor) transfers to your name at the Land Department
- Post-handover: snagging list, furnishing (if not pre-furnished), management desk onboarding, listing on platforms; budget 2-4 months from handover to first rental income
Full process walkthrough at due diligence step-by-step and the complete buying guide.
For area-specific context, the Rawai property guide covers south Phuket fundamentals and the Bang Tao area guide covers the north-west corridor in detail.
Reservation to rental income: realistic timeline
| Phase | Duration |
|---|---|
| Reservation + lawyer review | 2-4 weeks |
| SPA signing + down payment | 30-60 days from reservation |
| Construction (2026 launch, 2027-28 delivery) | 18-36 months |
| Snagging + furnishing (if not pre-furnished) | 6-12 weeks post-handover |
| Listing setup, photography, review accumulation | 4-8 weeks |
| A listing with enough review history to price properly | 2-3 months after listing |
For a 2026 launch with Q1 2027 delivery (Wekata 3), the timeline is compressed, a realistic expectation is rental income by Q3 2027. For a 2028-29 delivery project, first stable income is more likely 2029-2030.
Buyers who need cashflow within 18 months should focus on near-completion or finished projects, not new launches with 24-36 month build periods.
Buyer Profiles: Which Project Suits You?
| Your priority | Best match | Why |
|---|---|---|
| Lowest all-in entry, letting from handover | Wekata 3 | 4.4M THB fully furnished, Q1 2027, Kata’s short-let demand |
| South Phuket value, minimal risk | Dominion Rawai | Near-completion, 68 units, Rawai demand |
| Lifestyle villa, Bang Tao/Surin | Rainpalm Villas | Modern Tropical, 21 villas, 24M THB entry |
| Maximum scarcity, appreciation play | Mono Oxygen Phase 2 | 5 villas only, Choeng Thale, Q2 2027 |
| Best lifestyle, finished today | ISOLA Phuket | Finished, Layan, 35M THB entry, inspect now |
| Laguna corridor access, mid-budget | Skypark Elara Lakelands | Laguna amenity access, 5-8M THB range |
| Absolute lowest ticket | The Title Balcony | Entry 3-4M THB, proven The Title track record |
Looking for the right property in Phuket?
Our experts send a shortlist within 2 hours. 0% buyer commission.
Pre-reservation checklist: before you wire anything
| Item | Status |
|---|---|
| Developer has delivered a comparable project on time | Verify |
| EIA approval and building permit confirmed in writing | Verify |
| Foreign freehold quota for your specific unit confirmed | Verify |
| Independent Thai lawyer engaged and reviewed SPA | Essential |
| Payment schedule is milestone-linked, under 30% upfront before ground break | Verify |
| FET procedure documented for each tranche with lawyer | Verify |
| Rental management operator named (not “TBD”) | Verify |
| Unit-level quota reservation letter provided | Verify |
Two failed items = do not proceed. The 2026 launch pipeline is dense enough that a better-structured project is always available.
Bottom line: MORE Group’s 2026 verdict
For most first-time Phuket buyers, Wekata 3 is the most straightforward entry: low total cost, furnished delivery, short construction window, proven Kata location. For buyers who want south Phuket with minimal remaining construction risk, Dominion Rawai is the clearest near-completion case. In the villa segment, ISOLA is finished and inspectable now; Mono Oxygen Phase 2 offers Bang Tao scarcity at 5 units. Rainpalm serves the lifestyle buyer who wants villa scale without the luxury-tier entry.
The worst approach in 2026 is chasing whichever launch is marketing most aggressively. Launch budgets do not correlate with project quality, diligence on developer track record, EIA status, and management operator is what separates strong purchases from expensive mistakes.
We track live availability, quota status, and net yield models across all shortlisted projects. We don’t take developer commissions that conflict with buyer interests, our role is to match clients with the right project, not the highest-margin one.
For a current availability check and independent project comparison, contact the MORE Group Phuket team directly.
Frequently Asked Questions
In 2026 the standout launches and completions are Wekata 3 (Kata Beach, from 4.4M THB fully furnished, Q1 2027), Dominion Rawai (near completion, from 4.99M THB, 68 units in south Phuket), Mono Oxygen Bang Tao Phase 2 (5 pool villas only, Choeng Thale, 23.95M THB, Q2 2027), Rainpalm Villas (Bang Tao/Surin, 24.2-43M THB, 21 villas), and ISOLA Phuket (Layan, finished, 35-75M THB, 12 villas). Best fit depends on budget, timeline, and whether you prioritise yield or lifestyle.
None can be ranked on yield, because none is published for Phuket, and the claim that Kata has 'over a decade of proven short-stay occupancy data' is the part to be clearest about: no such series exists for privately owned units anywhere in Thailand. Both figures are withdrawn. What the price list holds: Wekata 3 has 35 priced units from 4,400,000 THB at 157,031 per square metre and Dominion Rawai 16 from 4,990,000 at 162,000, both above their area medians of 152,000 and 145,000. A management fee of 30-40% of gross is contractual and is the number to obtain in writing.
Wekata 3 starts from 4.4M THB fully furnished, one of the lowest all-in prices for a 2026-delivery boutique project in an established tourist zone. The Title Balcony line offers entry units from approximately 3-4M THB for buyers seeking the lowest absolute price point in the new-build market.
For buyers who want to minimise construction risk and receive rental income sooner, near-completion projects like Dominion Rawai and finished ISOLA Phuket are the better choice in 2026. The residual discount is smaller (8-15% vs 20-25% at early launch) but the risk is substantially lower and delivery is months away, not years.
Yes. Condominiums like Wekata 3, Dominion Rawai, and Skypark Elara offer freehold (Chanote title) under the 49% foreign quota rule. Pool villas like Rainpalm, Mono Oxygen, and ISOLA are typically structured as long-term leasehold (30+30 years) for foreign buyers, with the land held by a Thai company. Confirm the exact structure per unit with an independent Thai lawyer before reserving.

Maksim Shchegolev
Founder, MORE Group
Founder of MORE Group. Four years in investment banking before moving to Phuket, where he has worked in the local property market since 2018. Oversees developer relationships and every engagement above $300K.
About MORE Group →Get a Focused Phuket Property Shortlist
Share budget, area and goal. We will reply with suitable live projects, not a generic catalogue.
